Buy daydreamvillas.eu ?
We are moving the project
daydreamvillas.eu .
Are you interested in purchasing the domain
daydreamvillas.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy daydreamvillas.eu ?
How can I tell if there is still a mortgage on the property?
To determine if there is still a mortgage on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for any recorded documents related to the property, such as deeds of trust or mortgage documents. You can also contact the lender directly to inquire about the status of the mortgage. Additionally, you can hire a title company to conduct a title search on the property, which will reveal any existing liens or mortgages. **
Are mortgage interest rates rising? Are property prices in our village rising rapidly?
Mortgage interest rates have been rising gradually over the past few months, but they are still relatively low compared to historical averages. As for property prices in our village, they have been rising rapidly due to high demand and limited supply. This trend is likely to continue in the near future, making it a good time to invest in real estate in our village. **
Similar search terms for Mortgage
Top-Angebote
Products related to Mortgage:
-
NARS Sparked Liquid Eyeshadow liquid glitter eyeshadow shade HOT PROPERTY 3.5 mlNARS Sparked Liquid Eyeshadow, 3.5 ml, Eyeshadows for Women, Do you tend to hit the same few shades in your favourite eyeshadow palette but you just can’t do without them? Or are you travelling and can only fit the essentials in your toiletry bag? Thanks to its compact size, the NARS Sparked Liquid Eyeshadow eyeshadow won’t take up much room, so you can always have it on hand, be it by itself in your purse or as an accessory to your favourite palette. This allows you to give your lids a pop of colour or define the shape of your eyes to your liking, giving every makeup look a new dimension, no matter what your reason for getting them is. The formula ensures even pigment coverage, easy application and seamless blending without unwanted harsh transitions. Characteristics: long-lasting do not smudge in the crease of the eyelid washes out easily sparkling effect ophthalmologically tested30,80 £*Shipping: 3,99 £Secure redirect to the provider
-
"Pavilion Vacation Fund Ceramic Savings Bank - 6.5"""Save for your next adventure in style with this charming “Vacation Fund” stoneware money jar. Featuring a glossy ombre glaze, motivational fill lines, and a removable dollar-sign keychain, it’s a fun and functional way to reach your travel goals31,99 $*Shipping: 0,00 $Secure redirect to the provider
-
Doona Infant Car Seat & Stroller - Vacation (Limited Edition)Doona is the worlds first complete and fully integrated travel system, allowing you to move from car seat to stroller in seconds. The sleek and stylish design allows you to navigate the streets at ease, without disturbing your sleeping child when...600,00 $*Shipping: 0,00 $Secure redirect to the provider



-
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
-
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **
-
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **

What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
Why is the registered mortgage important for a loan, rather than the value of the property?
The registered mortgage is important for a loan because it serves as a legal guarantee for the lender that they have a claim on the property in case the borrower defaults on the loan. This provides security to the lender and reduces the risk associated with lending money. The value of the property is important for determining the loan amount and the terms of the loan, but the registered mortgage ensures that the lender has a legal right to the property in case of non-payment. **
Top-Angebote
Products related to Mortgage:
-
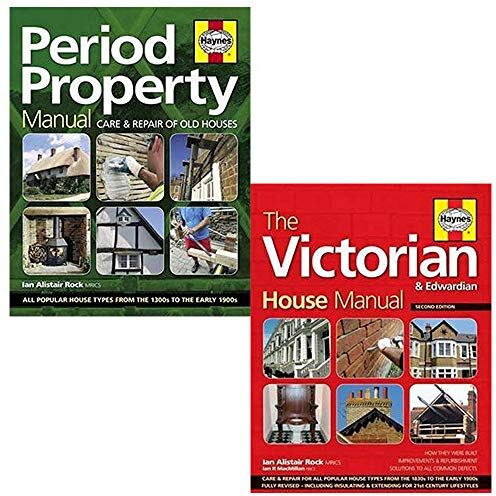
J H Haynes & Co Ltd Haynes Property Manual 2 Books Collection Set (The Victorian House, Period Property)The Victorian House Manual The Victorian House Manual (2nd Edition): How They Were Built, Improvements & Refurbishment, Solutions to All Common Defects Thinking of buying a Victorian or Edwardian house? Or maybe you already own one? Either way, this clearly written manual explains all you need to know about the care and repair of these classic properties. Today, many houses of this age are in need of extensive updating and maintenance, having suffered years of neglect. Some have been damaged by misguided home improvements or botched repairs using the wrong materials. Even newly refurbished properties can sometimes conceal dangerous structural alterations and shoddy build-quality. This unique manual provides detailed, expert advice, backed up with clear how to colour photographs, describing where to check for the critical danger signs and how to fix all common defects. Period Property Britain has a wonderfully rich stock of period houses - everything from medieval cottages to Georgian townhouses and Edwardian mansions. But many of these historic properties are now at risk. Some are unwittingly damaged by well-meaning owners or incompetent builders; others suffer long-term deterioration where mortgage lenders have imposed quick-fix 'remedies'. Despite being some of the most sustainable buildings on the planet, many old houses are now being subjected to ill-advised works to upgrade thermal efficiency, resulting in the destruction of the very qualities that make them so appealing, slashing their values. Haynes have come to the rescue with this clearly written, lavishly illustrated manual explaining the correct approach to care and repair - covering the full range of traditional materials. Every old house has a story to tell, so Haynes also show how to explore your home's history and strip back modern finishes to reveal long lost original features. This comprehensive manual is essential reading whether you want to get your hands dirty or just want to understand how old houses work and how to go about employing specialist craftsmen.19,99 £*Shipping: 2,99 £Secure redirect to the provider
-
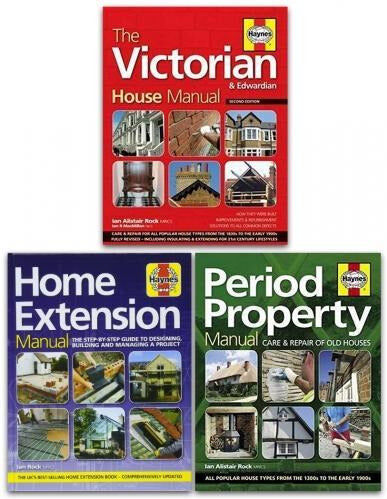
J H Haynes & Co Ltd Haynes Property Manual 3 Books Collection Set Home Extension The Victorian House Period PropertyTitles In this Set: The Victorian House Manual Home Extension Period Property The Victorian House Manual The Victorian House Manual (2nd Edition): How They Were Built, Improvements & Refurbishment, Solutions to All Common Defects Thinking of buying a Victorian or Edwardian house? Or maybe you already own one? Either way, this clearly written manual explains all you need to know about the care and repair of these classic properties. Today, many houses of this age are in need of extensive updating and maintenance, having suffered years of neglect. Some have been damaged by misguided home improvements or botched repairs using the wrong materials. Even newly refurbished properties can sometimes conceal dangerous structural alterations and shoddy build-quality. This unique manual provides detailed, expert advice, backed up with clear how to colour photographs, describing where to check for the critical danger signs and how to fix all common defects. Home ExtensionMany people are looking at ways to extend their homes rather than move house, but `getting the builders in' can be a recipe for disaster unless you really know what you are doing. Whether you plan to employ a building contractor or tackle some of the works yourself, this best-selling manual will show you how to stay firmly in control, resulting in a high-quality extension, completed on time and within budget. This new edition will include all the up-do-date information on complying with the latest Building Regs and Planning requirements, CAD design, energy-efficiency, under floor heating, bi-folds, liquid screeds, woodburning stoves and renewable energy. Period Property Britain has a wonderfully rich stock of period houses - everything from medieval cottages to Georgian townhouses and Edwardian mansions. But many of these historic properties are now at risk. Some are unwittingly damaged by well-meaning owners or incompetent builders; others suffer long-term deterioration where mortgage lenders have imposed quick-fix 'remedies'. Despite being some of the most sustainable buildings on the planet, many old houses are now being subjected to ill-advised works to upgrade thermal efficiency, resulting in the destruction of the very qualities that make them so appealing, slashing their values. Haynes have come to the rescue with this clearly written, lavishly illustrated manual explaining the correct approach to care and repair - covering the full range of traditional materials. Every old house has a story to tell, so Haynes also show how to explore your home's history and strip back modern finishes to reveal long lost original features. This comprehensive manual is essential reading whether you want to get your hands dirty or just want to understand how old houses work and how to go about employing specialist craftsmen.24,99 £*Shipping: 2,99 £Secure redirect to the provider
-
NARS Sparked Liquid Eyeshadow liquid glitter eyeshadow shade HOT PROPERTY 3.5 mlNARS Sparked Liquid Eyeshadow, 3.5 ml, Eyeshadows for Women, Do you tend to hit the same few shades in your favourite eyeshadow palette but you just can’t do without them? Or are you travelling and can only fit the essentials in your toiletry bag? Thanks to its compact size, the NARS Sparked Liquid Eyeshadow eyeshadow won’t take up much room, so you can always have it on hand, be it by itself in your purse or as an accessory to your favourite palette. This allows you to give your lids a pop of colour or define the shape of your eyes to your liking, giving every makeup look a new dimension, no matter what your reason for getting them is. The formula ensures even pigment coverage, easy application and seamless blending without unwanted harsh transitions. Characteristics: long-lasting do not smudge in the crease of the eyelid washes out easily sparkling effect ophthalmologically tested30,80 £*Shipping: 3,99 £Secure redirect to the provider
-
"Pavilion Vacation Fund Ceramic Savings Bank - 6.5"""Save for your next adventure in style with this charming “Vacation Fund” stoneware money jar. Featuring a glossy ombre glaze, motivational fill lines, and a removable dollar-sign keychain, it’s a fun and functional way to reach your travel goals31,99 $*Shipping: 0,00 $Secure redirect to the provider
-
How can I tell if there is still a mortgage on the property?
To determine if there is still a mortgage on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for any recorded documents related to the property, such as deeds of trust or mortgage documents. You can also contact the lender directly to inquire about the status of the mortgage. Additionally, you can hire a title company to conduct a title search on the property, which will reveal any existing liens or mortgages. **
-
Are mortgage interest rates rising? Are property prices in our village rising rapidly?
Mortgage interest rates have been rising gradually over the past few months, but they are still relatively low compared to historical averages. As for property prices in our village, they have been rising rapidly due to high demand and limited supply. This trend is likely to continue in the near future, making it a good time to invest in real estate in our village. **
-
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
-
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **
Similar search terms for Mortgage
-
Doona Infant Car Seat & Stroller - Vacation (Limited Edition)Doona is the worlds first complete and fully integrated travel system, allowing you to move from car seat to stroller in seconds. The sleek and stylish design allows you to navigate the streets at ease, without disturbing your sleeping child when...600,00 $*Shipping: 0,00 $Secure redirect to the provider
-
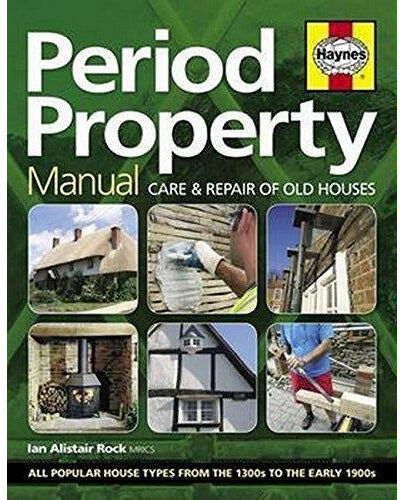
J H Haynes & Co Ltd Haynes Period Property Manual: Care And Repair Of Old HousesHaynes Period Property Manual: Care And Repair Of Old Houses Britain has a wonderfully rich stock of period houses - everything from medieval cottages to Georgian townhouses and Edwardian mansions. But many of these historic properties are now at risk. Some are unwittingly damaged by well-meaning owners or incompetent builders; others suffer long-term deterioration where mortgage lenders have imposed quick-fix 'remedies'. Despite being some of the most sustainable buildings on the planet; many old houses are now being subjected to ill-advised works to upgrade thermal efficiency; resulting in the destruction of the very qualities that make them so appealing; slashing their values. Haynes have come to the rescue with this clearly written; lavishly illustrated manual explaining the correct approach to care and repair - covering the full range of traditional materials.10,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **
-
What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
-
Why is the registered mortgage important for a loan, rather than the value of the property?
The registered mortgage is important for a loan because it serves as a legal guarantee for the lender that they have a claim on the property in case the borrower defaults on the loan. This provides security to the lender and reduces the risk associated with lending money. The value of the property is important for determining the loan amount and the terms of the loan, but the registered mortgage ensures that the lender has a legal right to the property in case of non-payment. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.